Some homeowners cut their flood insurance bill after updating one document. Others pay for a new elevation certificate and see no change at all. The difference comes down to a few numbers most people never read closely.
An elevation certificate isn’t paperwork you file and forget. It’s data that insurers plug into a formula. Understanding that formula helps you know when the certificate is worth getting, and when it isn’t.
How FEMA and Insurers Actually Read an Elevation Certificate
The National Flood Insurance Program (NFIP) doesn’t treat this certificate as a box to check. It uses the surveyed elevation data to help set your rate.
FEMA now rates most policies under a system called Risk Rating 2.0. This system pulls from many sources, not just one certificate. That means a certificate isn’t automatically required for every policy anymore.
But here’s the part that matters: submitting one can still help. If your certificate shows favorable numbers, insurers can use that data to adjust your rate downward. If you skip it, you may end up using more general flood risk data for your area instead, which isn’t always in your favor.
The One Number on the Certificate That Moves Your Premium Most
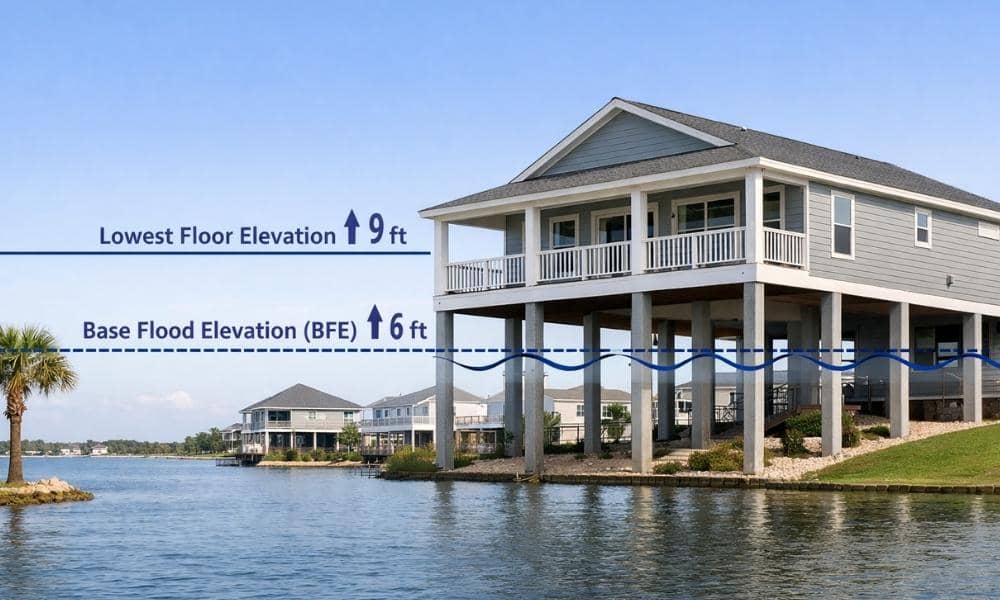
Your flood zone letter tells you general risk. It doesn’t set your exact rate. One specific measurement does most of that work: the relationship between your lowest floor elevation and the Base Flood Elevation (BFE) for your property.
BFE is the height floodwater is expected to reach during a major flood event. Your lowest floor elevation is the height of your home’s lowest level.
The math is simple. The higher your lowest floor sits above BFE, the better your rate tends to look. The lower it sits, especially below BFE, the higher your risk rating climbs.
This is a different question than “what flood zone am I in.” Two homes in the same zone can have very different elevation numbers, and very different premiums.
Why an Elevation Certificate Matters More in Some Flood Zones Than Others
Not every property benefits equally from this document. It matters most for homes sitting inside a Special Flood Hazard Area (SFHA), the zones FEMA considers highest risk.
In Virginia, that often means Zones AE or VE. You’ll find a lot of this along Tidewater, Hampton Roads, and the shoreline communities around the Chesapeake Bay. These areas face real flood and storm surge exposure, so elevation data carries more weight in the rate calculation.
If your property sits in Zone X, or another minimal-risk zone, an elevation certificate usually won’t move the needle much. The risk is already low, so there’s less for the certificate to adjust.
Situations Where an Elevation Certificate Won’t Change Your Rate
An elevation certificate isn’t a guaranteed discount. It’s a snapshot of facts, and sometimes those facts don’t help you.
If your certificate shows your lowest floor sits below BFE, it won’t lower your premium. In some cases, it confirms that your property carries higher risk than expected, which can raise your rate instead.
There’s another wrinkle. Under Risk Rating 2.0, some low-risk properties are already priced using other flood data sources. For those homes, ordering a certificate may not change anything, since the system isn’t leaning on that document in the first place.
Before paying for one, it helps to ask your insurance agent whether your specific property and policy type would actually benefit.
What Homeowners Can Do If the Elevation Certificate Works Against Them
A certificate that doesn’t help you isn’t the end of the road. A few legitimate paths can still bring your costs down over time.
Physical improvements. Raising the structure or adding flood vents can change your actual elevation numbers for the better on a future certificate.
Letter of Map Amendment (LOMA). If you believe your property was mapped into a high-risk zone by mistake, you can apply through FEMA to have that corrected. This won’t work for every property, but it’s worth checking if your land sits at the edge of a mapped flood zone.
Community Rating System (CRS). Some communities take extra steps on floodplain management, like better drainage projects or stricter building codes. Homes in CRS-participating communities can qualify for a modest discount, separate from anything on your individual certificate.
None of these are quick fixes. But they’re real options, and they’re worth a conversation with a licensed surveyor or your insurance agent before you assume your rate is fixed.